
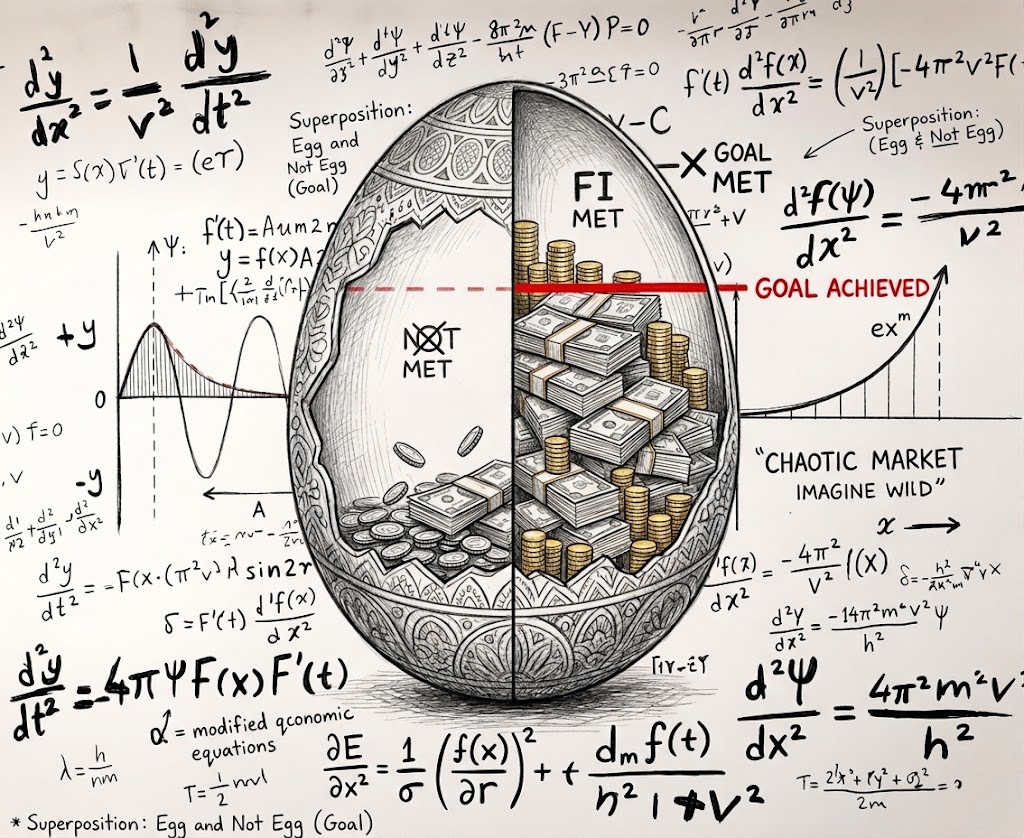
There’s a specific kind of magic in having a goal that, once met, completely changes your life. When the Nest Egg hits the right size, it grants ultimate permission to step away from the corporate machine. For the last two years, “The Number” has been my northern light. But with the finish line just inches away, I’ve done something counterintuitive.
I stopped checking the scoreboard.
I usually check my net worth five or six times a year out of pure curiosity, but it’s been four months since I last logged in. Why?
I am leaving the portfolio unchecked so it remains in a state of “superposition”—both FI and not FI—is a mental trick to help keep me moving forward until next summer. That is why it’s “Schrödinger’s” Nest Egg.
I don’t want to know if we’re FI just yet, for a few key reasons.
First, we’re dangerously close, if not already there. I thought we would cross the line this summer. To be honest, depending on how Padme’s index portfolio has tracked against the market compared to my conservative holdings, we might actually be FI today.
But I don’t want to look and be disappointed if we fall just short. The next time I run the numbers, I want the champagne already on ice. “The Number” itself isn’t what matters at this point, but mentally to me, it’s huge. It’s the target I’ve been focused on for years. I want to break the tape and not look back.
Second, I’ve committed, in my mind, to staying at work until next summer. This ensures Padme crosses her own line so she can retire, too. It was never her plan to step down this early, but given her high-stress job, she needs the option to pull the plug next spring. Me staying through the summer also puts the biggest home renovation bills firmly behind us.
If I look at the balance today and see we’ve officially crossed the finish line, grinding out the next several months is going to be a lot harder. So here I sit—probably FI, maybe not FI—only Schrödinger knows.
In quantum mechanics, observation collapses the wave function. In personal finance, opening Excel collapses the illusion. As long as the spreadsheet stays closed, I get to exist simultaneously as a bored corporate manager and a fully liberated retiree.
Yes, therapy would probably be easier than playing these mind games.
I’m calling these next several months “FI Eve.” FI Eve will run until Padme turns 50, which is the earliest her pension becomes claimable if we decide to take it early.
Coincidentally, our original timeline had us hitting our target right around her 50th birthday. That target got pulled forward six to eight months when I was cast out of the last Death Star with a year’s severance, only to land a new job three months later. In a stroke of cosmic irony, a painful corporate layoff became the ultimate speed boost, pulling our freedom day forward.
What felt like an orbital strike at the time turned out to be pure fuel. It’s funny how one of the worst days of your career can casually hand you the keys to your exit eight months early
However, being in FI Eve doesn’t mean we’re in “RE” Eve.
Retiring Early (RE) is tied far more to emotional readiness than a bank balance. Right as we may have hit our target, we are embarking on the highest-spending stretch of our lives—a new kitchen, renovations, big trips, and sending our first Jedi off to university. It’s our own capital-intensive final stretch before clear skies and smooth sailing.
For the first time ever in this next stretch our savings rate from our salaries will drop to zero. The portfolio will remain static, moving only on market returns as a real-world test drive. Redirecting 100% of incoming cash flow into current life—without the residual guilt of ‘I should be investing this’—is a complete psychological rewiring. It’s training wheels for learning how to spend vs how to accumulate.
.Until that massive spending year is behind us and our safe withdrawal rate normalizes back to 4%, I’m simply not emotionally ready for retirement.
Living off our income without adding a single dollar to savings for the first time in decades is a massive milestone in itself. Trialing a no savings “dry run”, watch our investments climb, adds a great trial layer to the plan. Hitting FI is a math problem; entering RE is an emotional transformation. Spending freely once retired will not be easy.
It’s going to be an interesting year, mostly to see how long my self-imposed ignorance holds up against my chronic desire to obsessively track numbers. Right now, I’m living in a glorious financial fever dream where I am both a stressed middle manager taking orders and a retired guy sipping coffee on a Tuesday morning.
Dying to know – or not?

 vaderonfire.com

Leave a comment